Saturday, March 20, 2021

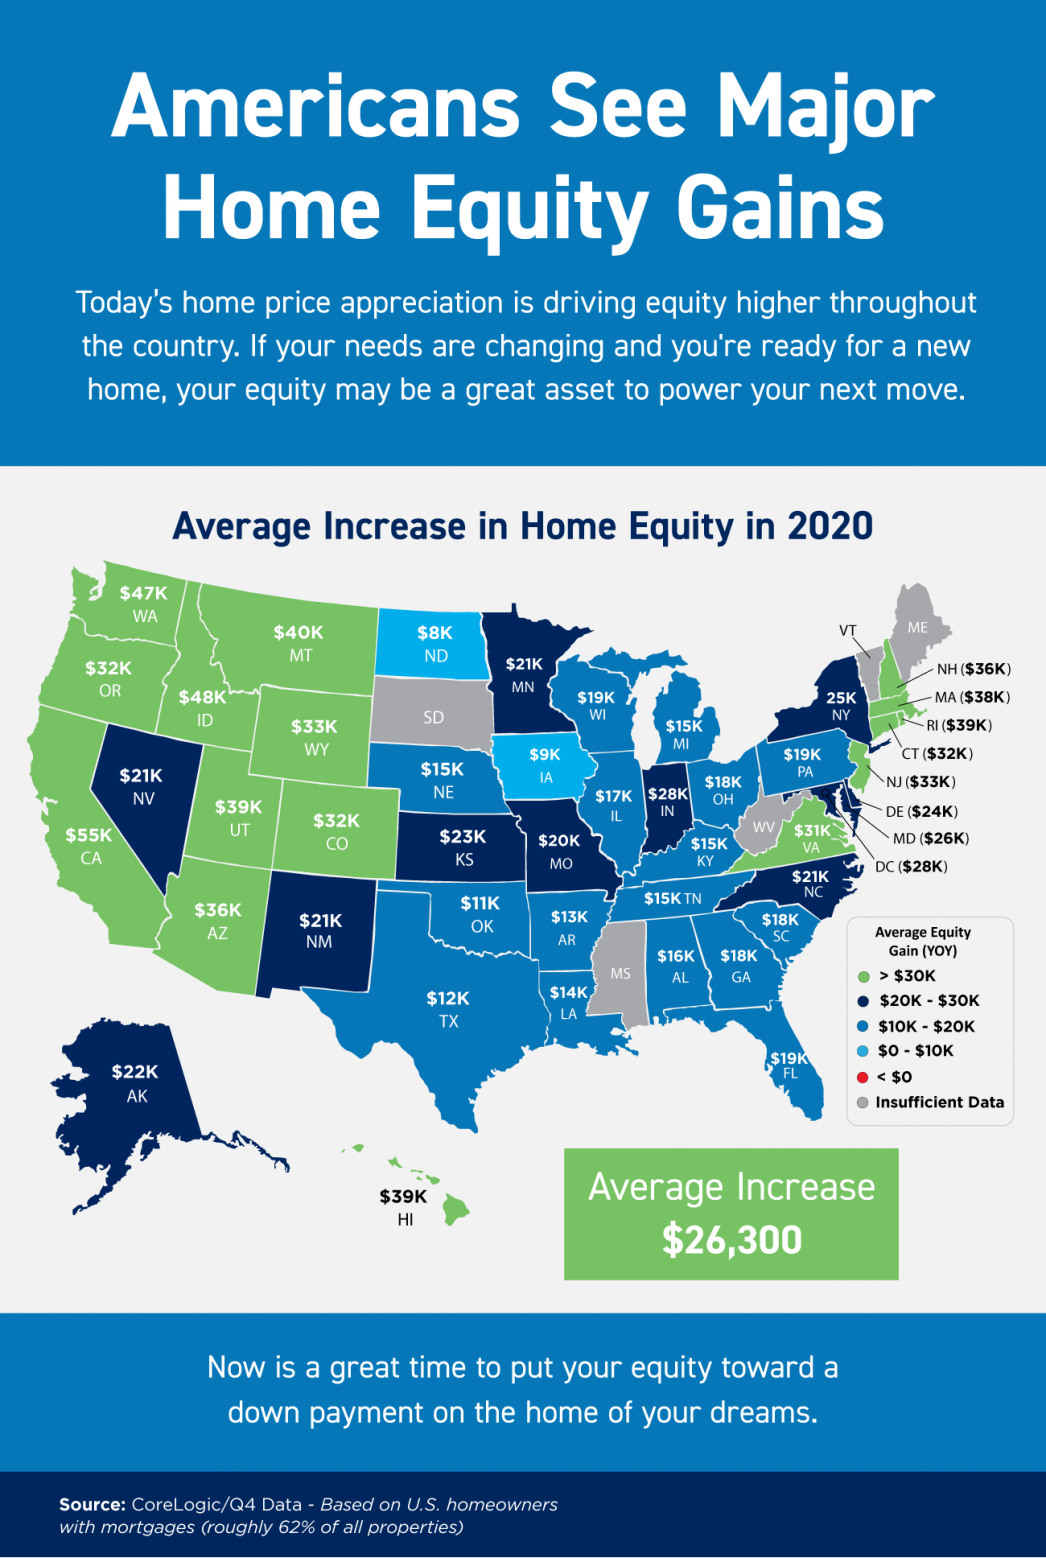
Americans See Major Home Equity Gains


Americans See Major Home Equity Gains [INFOGRAPHIC] | MyKCM


Some Highlights

  • Today’s home price appreciation is driving equity higher throughout the country.
  • If your needs are changing and you’re ready for a new home, your equity may be a great asset to power your next move.
  • Now is a great time to put your equity toward a down payment on the home of your dreams
For information on what your equity looks like, visit MoveWithMel.com

Melanie Wright
REALTOR
Big Block Realty North
Cell: 707-410-6634
CA DRE 01701771

Tuesday, February 12, 2013

Is now the time to consider a new home?


Our current market is experiencing an uptick in home values which is great news.  The bad news is that this market value increase is being caused by low inventory which means more buyers are looking for homes than homes are available to them.  This is causing most homes on the market to receive multiple offers and most of those may be over the asking price.  Most homes are receiving 10-20 offers each with some offers coming in $50,000 or more over the asking price.  I heard the other day that one home in the $250,000 range received 52 offers!!!  Another trend we are experiencing is sellers realizing that they are in the driver’s seat and asking buyers to completely remove any appraisal contingency, even if the buyer is using financing to purchase the home.

Because of this fierce competition, many home buyers are considering purchasing a brand new home if they can qualify for the increased prices that come along with new construction.  There are more homes available and less competition in the new home communities, but you can expect the prices to be 25-30% more for a comparable resale home in many cases.

Many buyers don’t know that a real estate agent can assist them with a new home purchase (if the builder has a co-op agreement).  All buyers must take their agent with them on their first visit to the community.  It is highly recommended that buyers have their own representation if allowed.  The builders sales agent’s primary focus is the seller/builder.  Having a Realtor on your side allows you to ask questions and have someone working only for you to make the process as smooth and understandable as possible.
New home under construction

Did you know that home builders have their own contract which is different than the standard CAR contract used in a resale purchase?  If you have been writing offers on resale homes in California, be prepared for a completely different offer and verbiage when buying a new construction home.

Builder confidence is at its highest in years and many new home communities are in the works.  Seeno is releasing new homes March 2nd in Fairfield and KB Homes has a new community in Vacaville.  Other communities are currently open as well.  Call me to take a new home tour or talk more about new homes vs. resale homes.  Make the Wright move today!

(707) 410-6634

Monday, August 27, 2012

Vacaville/Dixon area home prices are on the rise

Over the past 8-10 months the real estate market in Solano county and surrounding areas has been showing signs of life.  I wrote a post last October about buyers being subjected to limited inventory and having to make an offer quickly and many times having to offer over the list price to have a chance at getting their offer accepted.  We are seeing more and more of that currently which is causing home prices to go up month over month.

The same is happening accross the nation and in a recent USA today article they posted these statistics:

The National Association of Realtors said sales of previously occupied homes rose 2.3% from June, to a seasonally adjusted annual rate of 4.47 million. That was still the second-worst pace of the year and followed a decline in June. A 5.5 million rate is considered healthy.
The median price of homes sold rose 9.4% from a year ago — the sharpest increase since January 2006 — but the gain may be deceptively large. The Realtors association says that higher median prices are due to fewer sales of small, less-expensive homes.

The lower price ranges are definitely experiencing the most competition due to first time owner occupant buyers entering the market with record low interest rates on home loans as well as buyers paying all cash or utilizing large down payments to invest in real estate.  I am currently working with many buyers (both requiring financing or paying cash) looking to buy homes under $250,000.  All of them are experiencing competition when pursuing a home, meaning writing more than one offer to get one accepted as well as having to write over asking to be considered.  A few days ago, my buyer & I stood in line with 5 other agents/buyers to preview a home in North Vacaville priced at $200,000.

Many homes are selling in a few short days, some in hours of hitting the market.  Just to give you an idea of the local market, I pulled the following details today from BAREIS MLS.  I ran a search of homes in Solano County up to $250,000 (SFR/Condo and Farm/Ranch) and this is what I found:

  • Available homes: 192
  • Homes in escrow (have an accepted offer): 1163
  • Homes sold in past 3 months: 1041

If you are thinking now is the time to buy, it really is a great combination of affordable prices and extremely low interest rates.  But, here is a list to help you be better prepared when you start your search:

  1. Stay on top of the listings coming up and see them as soon as you can.  I offer a great service where listings come straight to your email.  Click here to request that be started for you.  Or you can do your own search as well. 
  2. Assume you will have to look at many homes and write multiple offers before you get an offer accepted.
  3. Don't be afraid to write an offer over the list price if you & your agent feel it can be supported by an appraisal.
  4. Lastly, if you will not be paying all cash, get pre-approved for a loan before going out to look at homes.  Your offer will not be considered most of the time if you can't provide written loan pre-approval with your offer.
Are you thinking about selling your home?  Due to the competition among buyers, now is a great time to sell as more buyers on the market demand more homes available to purchase.  Short sales (you owe more than your homes current value) are selling just as fast as fair market and REO (real estate owned) homes.  Wondering what your home is worth?  Request a FREE CMA today and let me help you sell your home quickly and for TOP DOLLAR in today's market!

Above excerpt pulled from http://www.usatoday.com/money/economy/housing/story/2012-08-22/existing-home-sales-july/57205914/1

Monday, October 24, 2011

Why do I need a "Pre-Approval" letter

One of the first steps to buying a home is getting pre-approved with a lender.  It is also a good idea to use a local lender that is familiar with local lending guidelines as well as loan programs you may be able to take advantage of.  Take the steps necessary to get a letter from the lender stating you are "pre-approved" for a loan in a specific price range. It's important to have this letter before you make a contract offer to buy real estate. Once you're pre-approved, you know what price range of homes you should be looking at.  
An example of loan programs that may be available to you are ZERO down financing through USDA rural housing loans or pay as little as .5% down with the CHF Platinum loan program*.  There are also many other great loan options such as Conventional, 3.5% down FHA or ZERO down VA financing (buyer must meet VA guidelines).  Plus, there may be individual city grant/loan assistance options as well.  Visit my preferred lenders website today to get pre-approved and find out about all of the unique lending opportunities available to you!
Contact Chris Kohler of Alpine Mortgage Planning today!
916-847-5912
For more information on loan programs click below:

*USDA rural housing loans have income limits and property must be in a pre-determined rural area.  Platinum Grant program has income limits and the 3% grant can be used toward your down payment or toward closing costs.

Monday, October 10, 2011

If at first you don't succeed...

Try, try again!  The real estate market in our area is showing signs of life and many homes are going into escrow quickly.  Some homes are experiencing multiple offers causing bidding wars and usually when that happens the home ends up selling for higher than list price.  If you are considering buying a home and are concerned that values may drop more, there may be cause to reconsider purchasing a home sooner than later.  Interest rates are amazing and home prices are at record lows.  Overall, home prices have been slowly increasing over the past 4 months.

I am working with roughly 8-10 active buyers in Solano county right now so I am seeing first hand what they are experiencing when they find a home they like.  Many times they write an offer at or above asking and they are still losing out to other buyers that have cash or have simply written a higher overall offer than theirs.  As the market pendulum swings the other way it's important to remember that there is still a lot of inventory on the market.  If you don't get the home you like the first time, keep looking and remember that you will find a home that works for you, even if you have to make a few compromises to get it.  And, make sure you are working with a Realtor that is as dedicated to finding you a great home as you are.  One of my buyers wrote 4 offers over a 3 month time span and after losing a few homes to other buyers (or simply having a bank reject his offer), he re-grouped and re-prioritized what he was looking for in a home and just found a wonderfully updated home which he was able to negotiate a price slightly under the list price.
Commitment and hard work are key to your home buying success!

You may also be noticing that when you call to inquire about a home you saw online, it's already in escrow.  Are you hearing that a lot lately?  If you are tired of missing out on homes that you like you need to get the listings coming to you.  Most MLS service providers (via a Realtor) can automatically update you via email when homes within your criteria hit the market.  Don't be left out!  Request your home search to be set up today.  Visit www.SolanoMoves.com

There will never be a perfect time to buy (once the bottom hits it is easy to miss) & their may never be the perfect home in your price range, but if you can be open to compromise and continuing to search for homes even if you have lost a few that you like, you will find a great home for a great price and will have a fantastic interest rate to top it off in today's real estate market.  Now truly is a fantastic time to buy a home!


Sunday, September 25, 2011

10 tips to avoid being the next victim of a home robbery

Our home is our castle and we work hard to provide for our families and buy the things we want to make our house a home.  When someone feels they have the right to take your belongings and our sense of security by breaking into our home and taking whatever they want leaves you with a sense of loss, fear and hopelessness.  Here are some great tips to protect yourself & your family from being the next victim of a home invasion.

Provided by ConsumerReports.com

A home is robbed every 14.6 seconds and the average dollar loss per burglary is $2,119, according to statistics just released by the Federal Bureau of Investigation. And that's the good news because burglaries were down slightly in 2010 compared to 2009. Sure you lock your doors and windows when you're not home (you'd be surprised how many people don't). But here are ten things that you're probably doing that make your home a target, and what you should do instead:


1. Leaving your garage door open or unlocked. Once inside the garage, a burglar can use any tools you haven't locked away to break into your home, out of sight of the neighbors. Interior doors between the garage and your home often aren't as strong as exterior doors and may not have deadbolt locks.
Instead: Always close and lock the garage door. Consider getting a garage-door opener with random codes that automatically reset.

2. Hiding spare keys. Burglars know about fake rocks and leprechaun statues and will check under doormats, in mailboxes, and over doorways.
Instead: Give a spare set to a neighbor or family member.

3. Storing ladders outdoors or in unlocked sheds. Burglars can use them to reach the roof and unprotected upper floor windows.
Instead: Keep ladders under lock and key.

4. Relying on silent alarm systems. Everyone hates noisy alarms, especially burglars. Smart thieves know that it can take as long as 10 to 20 minutes for the alarm company or cops to show up after an alarm has been tripped.
Instead: Have both silent and audible alarms.

5. Letting landscaping get overgrown. Tall hedges and shrubs near the house create hiding spots for burglars who may even use overhanging branches to climb onto your roof.
Instead: Trim any bushes and trees around your home.

6. Keeping your house in the dark. Like overgrown landscaping, poor exterior lighting creates shadows in which burglars can work unobserved.
Instead: Replace burned out bulbs promptly, add lighting where needed, and consider putting fixtures on motion sensors or light sensors so that they go on automatically.

7. Not securing sliding doors. These often make tempting targets.
Instead: When you're out, put a dowel down in the channel, so that the door can't be opened wide enough for a person to get through.

8. Relying on your dog to scare away burglars. While barking my deter amateurs, serious burglars know that dogs may back away from someone wielding a weapon, or get chummy if offered a treat laced with a tranquilizer.
Instead: Make your home look occupied by using timers to turn lights, radios, and TVs on and off in random patterns.

9. Leaving "goody" boxes by the curb. Nothing screams "I just got a brand new flat-screen, stereo, or other big-ticket item" better than boxes by the curb with your garbage cans.
Instead: Break down big boxes into small pieces and bundle them together so that you can't tell what was inside.

10. Posting vacation photos on Facebook. Burglars troll social media sites looking for targets.
Instead: Wait until you get back before sharing vacation details or make sure your security settings only allow trusted "friends" to see what you're up to.


Copyrighted 2009, Consumers Union of U.S., Inc. All Rights Reserved.

Friday, September 9, 2011

What is PMI?

In the real estate world we have a lot of acronyms and they can be a little confusing.  Many of you have heard of or seen PMI and may wonder what it means or how it works.  PMI stands for Private Mortgage Insurance.  Here is a bit more detail about PMI, when you will need to have it for a home loan and when you may be able to cancel you PMI coverage.


Private Mortgage Insurance

Normally, PMI is required for any home loan purchase with less than 20% down.  Private mortgage insurance is a type of insurance that helps protect the mortgage company against losses due to foreclosure. This protection is provided by private mortgage insurance companies and allows mortgage companies to accept lower down payments than would normally be allowed.

Private mortgage insurance also enables mortgage companies to grant loans that would otherwise be considered too risky to be purchased by third party investors like the Federal National Mortgage Association (FNMA) and the Federal Home Loan Mortgage Corporation (FHLMC). The ability to sell loans to these investors is critical to maintaining mortgage market liquidity, which in turn, allows mortgage companies to continue originating new loans.

PMI vs FHA MIP

Although the insurance protection concept is similar, there are differences between private mortgage insurance and FHA mortgage insurance. FHA insurance is a government-administered mortgage insurance program that does have certain restrictions. FHA has maximum regional loan limits that are lower than those with private mortgage insurance. FHA may be more expensive, take longer to receive approval, and have fewer payment plan options. FHA insurance lasts for the life of the loan, unlike private mortgage insurance which is cancelable in most circumstances. FHA is a good choice for some borrowers with credit history problems that might need special assistance.

PMI Cancellation

Mortgage insurance can usually be canceled by the home buyer after he or she has at least 20 percent equity in the home. Borrowers should contact their servicer to find out the procedure for canceling mortgage insurance when they think they have achieved 20 percent equity. Guidelines for canceling private mortgage insurance are set by investors. Typically, investors will require an appraisal on the property. The servicer can recommend qualified local appraisers.

Wednesday, August 17, 2011

What's happening in Dixon?

Dixon is a wonderful small town located in Solano County close to larger cities such as Sacramento and San Francisco.  It also borders the college town of Davis which offers large commercial shopping opportunities, amazing restaurant selections and beautiful parks.

Every Saturday from 9am-1pm enjoy fresh produce and other food & craft items at the certified Farmer’s Market through the Solano County Ag Department.  The farmer's market is located at Women's Improvement Club Park on the corners of C & North 1st Streets. 

At the same time as the farmers market, take an opportunity to check out the Dixon Used Book Store which is right next to the park and library.  They have amazing deals on used books for everyone.  We have purchased many children's books for my 2 year old and they are only a dime a piece. 


August 27th is the Downtown Dixon Business Associations 9th Annual Wine & Art Stroll.  The event will start in the Women's Improvement Club Park this year and continue throughout the downtown core along North First Street and including businesses on A, B, and Jackson Street. Tickets are available through the DDBA website DowntownDixon or they can be purchased at Saturday's Farmer's Markets for $20. They will cost $25 on the day of the event. Cost is for the commemorative wine glass and a map of where the various participating wineries are pouring. Live music will be at North First and A Street throughout the evening. Adults only please.


Looking for something to do with your little ones?  Stop by the Dixon Library for preschool storytime & crafts.  Every other Wednesday at 10:00am through October.  The next session will be August 24th and you must register for the craft portion.  Contact Katrina Bergen at 707-693-2747 with questions.


Dixon has so much to offer with that small town atmosphere so many of us enjoy and feel priviledged to call home.  If you are considering buying a home in Dixon, please visit my website SolanoMoves.com today.  I also assist home buyers & sellers in Solano & Yolo counties as well as some areas of Napa & Sacramento counties.

Thursday, July 28, 2011

Giving back to the community!

I have always been taught to be there for others and show compassion when people or animals are in need.  It's also a part of my nature to be a caretaker and look out for others that struggle to look out for themselves.  That's why I have always tried to reach out to the community in any way that I can. 

I was a volunteer with the VacaValley Kiwanis club for 2 years in 2007/2008.  One of those years I was the Key Club liason for Vacaville High School.  I also volunteered my time with Central Lab Rescue assisting them with adoption days and transporting labs to/from foster homes. 

My most proud accomplishment was becoming a big sister with Big Brothers Big Sisters of the North Bay.  I was matched with my "little" Brittny in April of 2008.  We were matched for 3 years and she is a very big part of my life & always will be.  I am an only child and this was something I had wanted to do since I was in high school.  I feel very grateful that BBBS was able to match me with such a wonderful young lady right here in Solano County.  Both of our lives are forever changed for the experience BBBS gave us!  If you have ever thought about becoming a "big", this program is an amazing opportunity and there are so many "littles" in need.  Please visit the BBBS Northbay website today!

In my real estate career, giving back is just as important.  After my first year or two selling homes I decided I wanted a way to make a difference by making a $50 donation in my clients name after close of escrow.  I give my clients the option from one of 3 charities that are near and dear to my heart for many reasons.  Those charities are:

-Shriner's Hospitals for Children  
-Solano County SPCA
-Susan G. Komen Foundation

I am grateful for my health & the opportunities I have been provided in my life from my family and friends.  This is my way of giving back to those that for whatever the reason may not have had those opportunities or have been dealt a bad hand over the years (four legged critters included.)  Please visit the websites above for more information about these wonderful organizations!


Wednesday, July 20, 2011

Be prepared & install a carbon monoxide detector in your home

Are you currently selling your home or planning to list your home in the near future?  With the new carbon monoxide detector law in effect, it is important to be proactive in installing the detector prior to entering into escrow to avoid hold ups with the loan or added costs for re-inspection.  Appraisers are now required to note if a carbon monoxide detector has been installed or not.

FYI....New HUD changes effective Immediately....please take note of the new requirements regarding Carbon Monoxide Detectors!!!

California Properties: Effective July 1, 2011, all California properties (purchases, refinances and on all loan programs) require a Carbon Monoxide Detector.

Since we do not want the borrowers to have to pay for a re-inspection fee ($150-$165) for the installation of a $45.00 detector, if the appraisers did not indicate if a detector is present, the Underwriter will condition for the borrower(s) to provide evidence of the installation of the detector (copy of the receipt for purchasing the detector and photo of the installed detector is sufficient).

We will not require a 1004D until August 1st to allow time for our AMC’s and borrowers to become compliant with this new California ordinance.

Please make sure all of your properties are equipped with a carbon monoxide Detector, and please make sure that this is pointed out to the appraiser at the time of inspection....

Information provided by Deanna Shimboff of Downtown Lending Group
http://www.downtownlendinggroup.com/
DRE LIC# 01848060

NMLS LIC # 230201

Monday, July 11, 2011

Carbon monoxide detectors required in all single family homes* as of July 1, 2011

In May 2010, the state of California enacted a law requiring home owners to install carbon monoxide detectors in their homes. According to the California Air Resources Board, 30 to 40 people die each year from carbon monoxide poisoning. The senate bill, also known as the Carbon Monoxide Poisoning Prevention Act, states that those deaths were avoidable. According to the bill, the California law will help prevent further deaths and increase awareness.

Timeline
Although the bill was signed into law in 2010, California residents must have carbon monoxide detectors in their homes as of July 1, 2011. This timeline applies only to single-family homes that have appliances that burn fossil fuels or homes that have attached garages or fireplaces. For all other types of housing, such as apartments and hotels, detectors should be in place as of January 1, 2013. Types of fossil fuels include wood, gas and oil.

Detector
According to the senate bill, the detector must sound an audible warning once carbon monoxide is detected. It also must be powered by a battery, or if it is plugged in, have a battery for a backup. The detector also must be certified by national testing labs, such as the Underwriters Laboratories. The packaging on the carbon monoxide detector will state this. If the CO detector is also a smoke detector, it must still meet the above standards and must sound an alarm that is different than the smoke alarm. Carbon monoxide detectors typically can be purchased for about $20 and up.

Exemptions
Although the law targets units that are occupied by humans, the law exempts state and local government property, as well as property owned by the University of California Regents. The law requires local jurisdictions to comply; however, they may amend their current ordinances to fall more in line with the law.

Fines
California law states that anyone who does not comply with the law may face a $200 fine. However, residents will receive a notice of 30 days to correct any violations before they will be fined.


Read more: California Law on Carbon Monoxide Detector Requirements
eHow.com http://www.ehow.com/list_6674598_california-carbon-monoxide-detector-requirements.html#ixzz1RpbDFrCV

Sunday, June 5, 2011

Location IS a factor

I was working on a BPO (broker price opinion) the other day and as I was doing my inspection I realized again the importance of location on the value of a home. The home is in move-in condition, built in the 60’s, but with some modern updating. It’s a large single story with huge kitchen along with large living area and bedrooms. It also offers a large corner lot with in-ground pool. From the description of the home, you would expect it to have buyers knocking down the door to buy it. Before previewing the home, I assumed there must be some issues with the structure and the price was too high for its condition. When I got to the home, I realized it’s less than desirable location on a main street into town on a busy corner lot. It’s proximity to commercial businesses doesn’t help much either.

What is a seller to do when they have maintained their home and its features are what many home buyers are looking for, but the placement of the home is poor, leaving the home owner with limited buyers to pursue the property? You can’t change the location of the home and putting more money into a home that doesn’t need it won’t be profitable either. The only true option for the home owner is to drop the price to compensate for its poor location. This isn’t music to a home seller’s ears, but if you have to sell your home, this may be the only option.

The same rings true for home buyers looking to purchase. If you love the home, but not the location, you can attempt to negotiate the price, but assume that you will be in the same situation when you go to sell the home so take that into consideration when you make your offer. Location is a large part of what home buyers use when deciding on a home to buy. Whether it’s to find a home in a desirable school district/neighborhood or avoiding a busy street due to traffic noise or child safety, that will always affect its market value in a positive or negative way.

Wednesday, April 27, 2011

Suggestions on how to stop losing homes to higher bidders

Q: My daughter and her husband-to-be, who are both 21, are trying to buy a house and have put many offers in on various homes. They already are preapproved for the amount they need.

Every time they put an offer in, even on houses that have no other offers, and that have been on the market for a long time, all of a sudden many offers come in -- sometimes within 24 hours!

Then the bank goes with the higher offer, which confuses them because their agent told them there were no other offers. This has been very depressing for them.

They are getting married in June and would like to purchase a home before then, so they have a home to move into after the wedding (they both still live with their parents). Is there anything they can do to resolve this problem?
A: Being a buyer in today's market is nearly as frustrating as being a seller. You read and hear all day long about what a strong buyer's market it's supposed to be and what great deals there are to be had via foreclosures and short sales.

But when you start making offers on properties, you find that the banks are nowhere near as willing to negotiate as you expected, and that many of the bank-owned homes cannot be bought without prevailing over a sea of other offers.

Depressing and frustrating -- yes. But there are some strategies they can and should put into play to better their chances going forward.

With an individual seller, you can minimize the chances of being outbid unawares in a couple of ways. You can put a very, very short time frame on your offer, eliminating a window of opportunity for other buyers to swoop in on the property.

Also, most listing agents in "regular" sales want their clients to get the highest possible price for their home, so it's common for them to ring up any previous offerors to let them know when additional offers have come in, to give them an opportunity to increase their offers or otherwise make them more competitive.

You can't force a bank to respond to your offer in a very short time frame, or in any time frame at all, for that matter.

But what your daughter and future son-in-law can do is go into these transactions with the lessons they've learned thus far.

Whatever it is that caused them to be interested in this property at this point in time could very well be inspiring other buyers to make an offer at the same exact time. So, even when their agent is told that there are no other offers at the time they make theirs, they need to do several things.

First, they need to enlist their agent to stay in very close contact with the listing agent -- as often as two or three times a day is not overkill -- once their offer is submitted.

Your daughter's agent should not only be calling the listing agent frequently to check and see whether other offers have come in -- they should also be asking the listing agent upfront to notify them if additional offers come in. That way, your daughter and her fiancé may at least get the chance to try to compete with the other offers.

Additionally, your daughter should consider changing her approach to formulating the price she offers for a home. She will have a better shot at getting a home if she offers a price more in line with the recent sales in the area, versus just offering something below or even at whatever the list price is on the assumption that she has no competition.

Every time she wants to make an offer, she and her mate should sit down with her agent and get an analysis of the recent sales of similar properties in the area. If she's making an offer on a bank-owned property, she should look at those sorts of sales. It's critical that she not only look at the recent comps' list price, or sale price, but their list-price-to-sale-price ratio.

For example, if a home's list price is $100,000 and it sells for $110,000, the list-price-to-sale-price ratio is 110 percent.

From what you've said, it seems that it's pretty common for these homes to sell over asking. If she can work with her agent to determine how much, on average, over asking these homes typically sell for, then she can apply that ratio to the list price of the home for which she wants to place an offer.

So, for example, if the other homes are selling for 107 percent of their asking price and she is seriously interested in buying a home that is listed for $125,000, she would multiply $125,000 by 107 percent and consider an offer price of $133,750.

Yes, that may mean that she goes in with an offer over the asking price, even in a situation where she has been told there are no other offers. But if the recent comparable sales justify that value, and it is within the price range she can afford to pay, that may be necessary to avoid being chronically overbid and secure the home in which to start her family.

Some buyers get hung up on the idea that they are "overpaying" if they make an above-asking offer, but the reality is that the list price is not the actual price of the home -- it's a starting point for upwards or downwards negotiations, depending on the local market dynamics and how the list price was set vis-à-vis the fair market value of the home.

Getting a great deal is not necessarily the same as paying at or below asking; just think -- if the list price is set too high, then offering to pay it isn't a better deal than if you offer above-asking on a place where the list price is set way too low. This is why it's so critical to rely heavily on an analysis of recent comparable sales to drive your offer price, rather than just on the list price or what the listing agent tells you.

Further, no house is a good deal if you don't get it, which may be the learning that your daughter and her fiancé are experiencing. And given that prices have rolled back to 2003 levels in many areas, whatever they pay will undoubtedly be a great deal, from that perspective.

Tara-Nicholle Nelson is an author and the Consumer Ambassador and Educator for Trulia.com.
Thursday, February 24, 2011

Are you considering a short sale-you may qualify for HAFA!

Home Affordable Foreclosure Alternatives (HAFA) Program

If your mortgage payment is unaffordable and you are interested in transitioning to more affordable housing, you may be eligible for a short sale or deed-in-lieu of foreclosure through HAFA. The benefit of a HAFA short sale is that you are no longer responsible for the difference between what you owe on your mortgage and the amount that your home sells for. You will also receive $3,000 in relocation assistance upon successful closing of your short saleIn a short sale, the servicer allows you to list and sell the mortgaged property with the understanding that the net proceeds from the sale may be less than the total amount due on the first mortgage. or deed-in-lieu of foreclosureWith a deed-in-lieu of foreclosure, you voluntarily transfer ownership of your property to the servicer— provided the title is free and clear of mortgages, liens, and encumbrances. Generally, if you make a good faith effort to sell your property but are not successful, a servicer may consider a deed-in-lieu of foreclosure.

Eligibility*

You may be eligible to apply if you meet all of the following:

•You live in the home or have lived there in the last 12 months.

•You have a documented financial hardship.

•You have not purchased a new house within the last 12 months.

•Your first mortgage is less than $729,750.

•You obtained your mortgage on or before January 1, 2009.

•You must not have been convicted within the last 10 years of felony larceny, theft, fraud or forgery, money laundering or tax evasion, in connection with a mortgage or real estate transaction.

*Eligibility criteria are for guidance only. Contact your mortgage servicer to see if you qualify for HAFA.

Program Availability

HAFA is available for mortgages that are owned or guaranteed by Fannie Mae and Freddie Mac or serviced by over 100 HAMP participating servicers. A list of HAMP participating servicers can be found here.

For More Information

If you have additional questions about getting mortgage help, contact one of our housing advisors at (888) 995-HOPE (4673). These HUD-approved housing counselors will help you understand your options, design a plan to suit your individual situation, and prepare your application. Research shows that homeowners who work with housing counselors like these are more successful and have better long-term outcomes. There is no cost to you for this valuable, around-the-clock service. Help is available in more than 160 languages.

The above information was pulled directly from http://www.makinghomeaffordable.gov/Pages/default.aspx
______________________________________________________________
If you are experiencing a hardship such as job loss or divorce, have a home that you owe more than it's worth or possibly facing foreclosure there is help for you.  I have assisted many homeowners through the short sale process which has allowed them to get a fresh start.  If you would like a free consultation about your options, please call or email me.  You can also visit my short sale website at http://www.ShortSaleQandA.com .  You are not alone in this process and I am here to help you every step of the way!

Cell: (707) 410-6634
melanie@solanomoves.com

Monday, February 21, 2011

Making a good first impression

You need to attract more buyers if you want to sell your home, and one way is to take good pictures. During a buyers' market, sellers must try to come up with better marketing techniques because there will be many more homes than buyers in the market.

A seller must look for a way to make the home stand out from all the others that are available, and one way to do so is to let potential buyers view a home through pictures. The point is that if buyers do not call, then you will not sell your house. However, in order to get buyers to call, they have to be interested in your house. You have to show the best aspects of your house through your pictures. Some agents will post two or three pictures of the outside of the house, and leave it at that, without any further consideration. However, most buyers are now beginning their home searches online, and good photographs are a way to entice and attract them. Many home buyers will simply go on to the next listing if there is not at least one good picture of the exterior of the home.

Buyers are first attracted visually to a home, and then they will begin to look at everything else. A good photo will have no other distractions because you want the eye of the buyer to focus on the home. Therefore, some pictures will need to be doctored or fixed up with photo editing software. It's important to try to crop the sidewalks and the street from the picture. If you have a great front yard, you want to showcase that and not the street leading up to it. You have to remember that the main idea behind the picture is to show the home in the best manner possible.

Prior to you (or if hiring a Realtor to sell your home, they would be taking the pictures for you in most instances) make sure that you mow the lawn and trim the bushes to make them look attractive. If you have pets, your front yard should show no evidence that there are pets. You also must remove vehicles, bicycles, toys and anything else that will create clutter in the picture from the driveway, front yard, or any other part of the front of the home that is being shown. You must include up-close photos of special features of the house, and try to include some angled photos to give the buyer's eye a different perspective.

It's also a good idea to stay away from shaded areas of the house because they will not show well, unless you are an excellent photographer, and you really know how to make use of shaded and light areas to create interest and contrast. If not, then you should try to take your pictures when the front of your house has the best light so that it can be seen well.

Prior to photos being taken, you should also make sure that you clear away any and all shrubs, bushes, plants and any other vegetation that may block a view to the front door or the path to the front door. You want to show that the way is open to your house, rather than show an obstructed view, and make sure that you avoid shooting into the sun. If you show off your exterior well, it will very likely interest buyers into wanting to know what is inside.

When moving to the interior of your home, it's important to take pictures that highlight it's best features, but also to show the home so the buyer feels like they are moving through it as they look at the pictures. You should always take pictures of the kitchen, baths, living areas and bedrooms along with the backyard if it is an important selling feature. When taking pictures of bedrooms, take a picture from every corner to find the best view of the room to share with buyers. Depending on how natural light is coming into the room, you may need to open or close blinds for the best picture. Obviously, if a room or feature does not show well or may be a detriment to intriguing a buyer to call for a showing, those pictures are not necesarry to include in the marketing of your home.

Some good pictures might generate the calls and interest that you are looking for and possibly bring better value to your home. As a real estate professional, I feel it is very important to take as many pictures as I can of my listings to market them to their full potential. I take pictures of all of my listings for my clients and put them into a professional slide show that is posted everywhere I advertise/market the home. If you are thinking about selling your home and would like assistance or advice from a Realtor, feel free to call me anytime for a FREE consultation.

Make the WRIGHT choice today!
http://www.solanomoves.com/
(707) 410-6634

Wednesday, July 28, 2010

Hardwood vs. Laminate Flooring - Which one is better for your household?

I’ve always loved the look & “feel” of hardwood much better than laminate flooring. It feels rich and warm over a colder, harder laminate. I wanted to install hardwood floors in the main living areas of my home, but have chosen not to as the cost is higher than laminate and I have 3 big dogs and a toddler boy running around my house so the concern of almost instant damage to the floors has kept me from doing it. Laminate flooring has come a long way since it first came out and many look just like hardwood. When the time comes (probably sooner than later) to rip up the carpet and pad in my home, I am sure a nice laminate wood floor will be the way I go. Below are some ways that hardwood and laminate differ and may help you choose what product is best for your next home flooring project.

Hardwood Flooring
The richness of natural hardwood flooring can add unmistakable charm to any room. Today's hardwood floors come in more species, widths and colors than ever before and are more durable. With proper care and maintenance hardwood flooring can last more than a lifetime and will add real value to your home.

Some hardwood floors are now offered with a click-lock, glueless tongue-and-groove locking system. No messy glues or nails needed. We will probably see even more in the near future.
-Wood floors are a natural, non-allergenic product
-Hardwood floors can add real value to a home
2 Basic types of hardwood floor construction:
Solid Wood Floors (prefinished & unfinished)
-Cut from tree as a solid piece of wood
-Plank widths vary from 2-1/4" to about 12"
-Plank thicknesses vary from 7/16" to about 3/4"
-Will react to changes in humidity
-Recommended for above grade installations
-Nail-down installation to a wood type sub floor
-Solid wood needs proper expansion allowances along vertical walls

Engineered Wood Floors (prefinished & some unfinished)
-3 to 9 wood plies glued &laminated together
-Plank thicknesses vary from 3/8" to about 9/16"
-Top finish veneer may be domestic or exotic wood specie
-Plank widths vary from 2-1/4" to about 7"
-Glue, float, staple, or nail-down on all grade levels
-Wood subfloors or dry concrete slabs
-Glueless engineered wood floors install similar to laminate floors
-Dimensionally stable, most may be net fitted to vertical walls.
-Less effected by humidity changes than solid wood floors

Unfinished hardwood floors (also called job-site finished)
-With a job-site finish they sand the floor smooth, less chance for overwood
-Custom stained colors, generally 2-3 coats added of finish
-This can be fairly messy, takes several days


Pre-finished hardwood floors (also called factory finished)

-Usually installs in less than a day
-Less messy than job-site finish
-Limited to manufacturer's colors

-Manufacturers can apply 7-10 coats of finish
-Factory finishes are extremely wear resistant
-Some manufacturers add aluminum oxide for additional durability
-Today's factory finishes are much easier to care for than the old waxed finishes.
-Prefinished trims are not an exact match to the floor.
_________________________________________________________________

-Wood accents available to create unique looks and patterned designs.
-Never clean or wet mop a hardwood floor with water. Water can dull the finish and permanently damage the wood floor.
-All hardwood floors can be scratched. Scratches in the finish layer are fairly easy to repair.
-Areas with lots of direct sunlight may effect the wood color over time
-Most hardwood floors can be used over radiant heat with some limitations
-Wood floor finishes can be used to restore the floors original beauty
-Mostly used for: living rooms, dining rooms, bedrooms, dens, and great rooms.


Laminate Floors
Laminate floors combine a realistic impression of real hardwood, stone and tile with an extremely durable finish. These floors have become a popular alternative to real hardwood and vinyl floors.
-Laminate floors are NOT real wood floors
-Laminate floors are extremely impact, scratch, sunlight fade and stain resistant
Although laminate floors are extremely tough, they can be scratched by big dogs or dragging heavy objects across the floor.

Laminate flooring come in 3 types:
Installer has to apply special glue
-Special glue is applied manually to the tongue & grooves of each plank.
-Floating floor installation
-Not very common anymore
Glueless floating laminate floors
-No glue, just click, or snap-fit lock planks together
-Most laminate floors are of this type
Factory pre-glued, floating laminate floors
-The glue is applied at the factory. Just moisten the plank tongue and insert into adjacent plank.
-Some laminates use this method, not many


-Trims and moldings are available for laminate floors. Moldings are laminated over a fiber core so they match the floor, or the moldings can also be made from real wood and color coordinate with the flooring.
Laminate flooring uses the floating installation method, which means:
-Laminate floors just rest on top of the subfloor. They are never secured or fastened to the substrate below. Instead they just lay on top of the substrate. Specially designed tongue-and-groove interlocking systems to secure planks together.
-Float entire floor over a variety of sub floor materials, such as plywood, OSB, existing vinyl flooring, concrete slabs, etc...
-You never have to glue-down, staple down, or nail-down laminate flooring.
-Even though these floors are floated the sub floor still must be level for locking planks together.

___________________________________________________________________
-Most laminate floors can be used anywhere within the home, including wet area (but may not be warrantied).
-Laminate floors do not need a wax or polish.
-Excessive moisture may affect a laminate floor's inner core and overall performance
-Laminate planks are not easily repaired. There are touch-up kits and chip repair kits, but difficult to find.
-Laminate floors require a thin, special padding underneath the planks so they can move freely.
-Laminate floors can be fairly noisy when walked on. Special underlayment paddings are made to help reduce the noise level.
-Glueless laminate floors are a very good do-it-yourself product
-Highly resistant to the effects of sunlight
-Most laminate floors can be used over radiant heated concrete slabs
-Mostly used for: family rooms, living rooms, dining rooms, bedrooms and dens.

Monday, July 26, 2010

5 things you should never put in the dishwasher

Wood: This includes wooden spoons, salad bowls, chopsticks, and cutting boards. Wood will swell and crack in the dishwasher. Cutting boards or bowls can split & break.

Knives: You can put your cheap butter knives in there, but never the larger, nicer ones. The harsh detergent will cause nicks and scratches on the blade, dulling it. Also, putting and removing sharp, large knives is likely to cause damage to the dishwasher rack itself.

Crystal/Hand-blown Glass: These items are not just sensitive to heat (they can crack), but abrasive detergent can chip and etch them as well, causing them to lose their brilliance. They should be gently hand washed and dried with a soft, lint free towel.

Pots & Pans: It's generally not a good idea to put pots & pans in the dishwasher. After running a few cycles on them, some pots and pans will end up with loose handles and seals/top coatings can come off. Additionally, here are particular types that should definitely not go into the dishwasher:

--Nonstick/Anodized Aluminum: The coating will wear out and break down and it will no longer be non-stick. This includes bakeware.

--Cast Iron: It will rust and lose its seasoning. After rinsing with water, heat on the stove to completely dry.

--Enameled Cast Iron: These are very prone to chipping. Plates and bowls may hit against the pot during the cycle.

--Aluminum: It's extremely vulnerable to nicks and scratches. This includes thermoses and water bottles.

Acrylic: Some of the acrylic tableware I have says top rack dishwasher safe, but in my experience it usually wears, dulls & eventually starts to crack.

Final tips: It's not always as easy as looking at the label to see whether something is dishwasher safe. Keep in mind that the environment inside a dishwasher is hot, humid, and wet. The detergent in abrasive. The water spray is not gentle (it's trying to spray off that caked-in spaghetti sauce). The top rack generally gets a gentler wash than the bottom. If you keep these things in mind, you'll be able to make better decisions about what to put in and what to keep out of the dishwasher.

Check back often for more household tips from Melanie Wright, Realtor/CDPE
(707) 410-6634